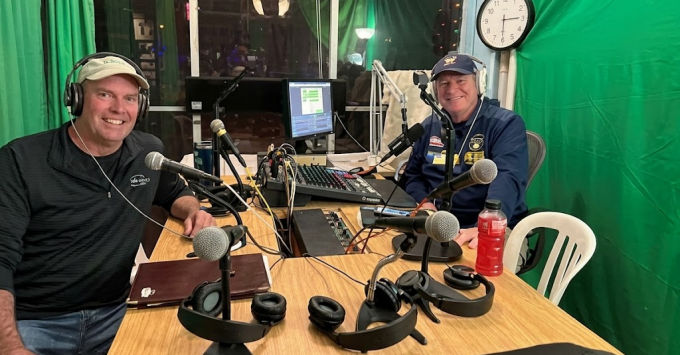
Listen to what Ron Philleo has to say.
THE ROBO SHOW
Transcript
MARK
You are listening to The Robo Show only on WXRW 1041, Milwaukee’s River West Radio. It’s the Robo Show. It’s the Robo Show. Hey, good evening. You are listening to the Robo Show. I am your host, Mark Robottom. We are on WXRW FM 104.1, streaming live on River Radio.com, and with me tonight, my guest is actually the equivalent of what Bob Uecker was to Johnny Carson. He’s a returning guest. Ron Philleo, of the Philleo Agency in Brookfield. Thanks for coming back, Ron.
RON PHILLEO
It’s great to be back here, Mark. Thanks for having.
MARK
Last time we were on the show, Ron, we talked about EV cars and, and, and how the insurance is different on them. And the main reason was batteries.
RON PHILLEO
That’s a big, big part of it. Yeah. I mean, if they get damaged, they’re expensive to fix.
MARK
Right. So that’s why the repair costs versus gas cars are really higher right now. And. But you said that gap was closing too.
RON PHILLEO
Well, as more shops learn how to work on them, more technicians want to learn to work on them. Parts become more available and they have more lost data. I think that gap will close. I don’t know if it’ll ever be one for one, but I think it’ll get closer.
MARK
All right, then we also talk about why renters insurance is important and the landlord covers none of your stuff.
RON PHILLEO
Yeah, it’s a big misconception that people like, well, I don’t need renters insurance. My landlord has insurance. He doesn’t cover any of your stuff. All your personal property, that’s one thing. But your larger exposure as a tenant is going to be your liability exposure. That is, let’s say you start a fire in your unit, you know, you put, put a pizza in the oven, you fall asleep, the place starts on fire. Not only is your unit damaged, but the, it’s the actual, the building is damaged because that’s the owner’s property. And now maybe other units are damaged and their personal property, all these things start to escalate and you can be held responsible. So the liability portion is really important on a renter’s policy.
MARK
Yeah. Well, the thing that really shocked me last, last time you were on the show was that you said that condo insurance, like 90% of the policies were poorly written.
RON PHILLEO
Yeah, it’s a shocking number and it amazes me every day. Nine out of 10 clients that come in our office with a condo policy, it’s written incorrectly. It’s written like a renter’s policy. People don’t understand. You own that ins the unit and you have to replace everything. So you have to account for all that personal property. You’re essentially rebuilding an entire house without the exterior walls. And that’s where we see it always go wrong.
MARK
Hey, we’re moving into winter here now in Wisconsin and I want to talk about insurance claims nobody sees coming, you know, frozen pipes, ice dams, snowblower accidents, and leaving your home unattended in winter. And let’s say, you know, you go to Florida for three weeks, you, you come home to a flooded house.
RON PHILLEO
Yeah.
MARK
Are you covered?
RON PHILLEO
So that’s one of the things insurance companies are concerned about all the time. In winter is a vacant home. You know, in summer we’re more worried about things like vandalism or crime, those kinds of things. In winter, it’s frozen pipes. And once your heat source stops working, it doesn’t take long to freeze those pipes. They burst and it causes a ton of damage. It’s the equivalent to having a fire in your home.
MARK
Wow.
RON PHILLEO
Yeah. So that’s what they’re worried about. A couple of things you can do. You know, you say claims you don’t see coming. Well, you can actually nowadays with the technology, see what’s coming. Most thermostats nowadays can be connected to online and you can get an alert if their heat drops below a certain part, you know, certain set temperature in your home. We recommend never going below 60, maybe 58. If you fail to maintain heat in your home, your insurance company can actually exclude the claim.
MARK
I believe it.
RON PHILLEO
Yeah. So people that intentionally turn their heat way down, insurance companies, you didn’t maintain heat in the home. You burst a pipe. That was your. That’s on you. That’s not on us.
MARK
Yeah, but I saved $27.
RON PHILLEO
Right, right. Yeah, you did save a couple of bucks. So going away, if you’re going to be leaving your home for an extended period of time, have someone check on your house every couple days that, that have your thermostat tied into the Internet to give you alerts about a minimum temperature that you set. And, and the other thing is water sensors. If a pipe burst, you can have sensors set on your intake of your water meter. If there’s not supposed to be any water flowing, it will alert you.
MARK
Nice. So.
RON PHILLEO
If a pipe bursts all of a sudden, there’s lots of water flowing. What is going on?
MARK
Right.
RON PHILLEO
So there’s lots of things you can do. And some companies actually require these for things like up north properties like cabins that aren’t Used all the time. They’ll require you as a requirement of the insurance for them to ensure you that you have these things.
MARK
Well, that was kind of like we talked about the requirement for renters insurance that landlords have for this, especially for the new renters. You know, that first year you got to be covered. Yeah, yeah,.
RON PHILLEO
Yeah. Proof of coverage and you know, it’s just hard, it’s hard to logistically keep track of it. But a lot of them. First year, right? Yeah,.
MARK
Yeah. Well, we’re going to talk about, you know, homeowners and liability and umbrella policies. Why do you, what do you, what can you tell us about umbrella policies for liability, Ron? Why are they so important today?
RON PHILLEO
I’ll tell you, everybody needs one.
MARK
Everybody,.
RON PHILLEO
Everybody.
MARK
It used to be just if you had a small business or. I remember, you know, when I started my business, I had to have an umbrella policy. It was like a million dollars to get, you know, sign a contract with some of these larger companies. I mean today that’s just, I don’t know. That doesn’t, doesn’t faze me at all. To have an umbrella.
RON PHILLEO
No. And how umbrella policies work, a lot of people aren’t familiar with those, but what they do is, I’ll go on a typical auto and home because most people can relate to that. Rather than commercial, there’s different ones for commercial. But typically you have your auto policy that has a set limit of liability. Right. Like we’re going to insure you to a certain number.
MARK
Exactly.
RON PHILLEO
And that number may be 300,000, 500,000. And if a claim exceeds that number and you don’t have an umbrella now you’re on your own. So you hurt somebody severely in an accident. By the way, it doesn’t take much to get over 100,000, 300,000 or 500,000. We see claims exceed that all the time. So once that number on your auto policy is hit, the insurance company has no more obligation to defend you or pay anything else. And they won’t. That’s where the umbrella comes in. The umbrella picks up where your underlying coverage on your auto, your home policy stopped and it usually it’s sold in increments of million dollars. So do you want a 1 million, 2 million, 3 million, 4 million? We can keep going up. Right now we’re working with, we work with several clients at over $10 million umbrellas. That’s for high net worth people. That’s not uncommon nowadays.
MARK
Okay, my house is worth 850,000 and you want me to cover it for 1.2 million is that just because you’re going to make a bigger commission, Ron.
RON PHILLEO
Sure. Well, you know, that’s part of the reality. But what happens is you’re talking, you’re switching out of replacement costs on homes. That’s a common thing that comes up all the time. People go, well, I’m like, well, you need to insure your home for, you know, 900,000. They go, well, I just got my assessment. It’s for 700,000. Or I talked to my real estate guy and he said, we can sell it for 800,000. Why don’t we insure for 900,000? Replacement costs is one of the things that we explain to clients all the time. We put a big emphasis on education with our clients and it’s, we’re not worried about what the home sells for or what it is assessed for or what it’s appraised for. The number one we’re concerned, concern that we have is that what is it going to take to rebuild this home?
MARK
Yeah.
RON PHILLEO
And you know, we’re not concerned with the land values or anything. And people are amazed at how much it costs to rebuild a simple home nowadays.
MARK
Yeah, yeah, right. I believe that. I want to talk about something that we really did talk about beforehand, but you just said, you know, we really want to educate our, our customers. And I think that’s so important, especially when you’re in the service industry and industry like me, you know, that everybody on both sides really understands what this is all about. So, you know, when you’re asking somebody to pay a premium above what the tax valuation of their property is, you know, I think it’s really important to establish trust and confidence in them so that they know that that extra premium, if there’s a claim, they’re going to be so grateful that you took the time to break that down. And, and I mean, you said 90% of condo policies are written wrong. Are people just not reading their, their coverages and don’t really understand what they’re getting because they’re not getting educated by their insurance agent.
RON PHILLEO
Yeah, I,.
MARK
I mean, I’m not knocking,.
RON PHILLEO
I don’t.
MARK
Say 80, 20 rule.
RON PHILLEO
No. And I, the, you know, the, I try not to put it on the consumer so much. Who they choose as an advisor is going to be the most important decision that they make with their insurance because the advisor is the one that’s going to recommend coverages for them. I don’t expect my clients to walk in and say, here’s what I want. And we don’t expect to be order takers. We expect to be advisors and to walk people through what coverage they need. So the education is a huge thing. We believe that an educated client makes good decisions. And I want to give that client confidence through our education to make those decisions. And that’s what we do. It’s really hard to select something you’re not aware of. So we spend time with our clients to go through and say, this is what this does. Here’s our recommendation on yes or no. But everybody’s got to know what their options are. We don’t make decisions for our clients, give them recommendations, but at the end of the day, they need to know how it works and then they can make a decision.
MARK
Yeah, we’re going to talk about liability. One of the things that just drives me crazy as it is, as a licensed driver in Wisconsin, and there are a lot of them are these people on these scooters, you know, and I just. I can’t believe that. You know what I mean? What does it take to get a scooter? And what. How many accidents a day are there with these scooters? I gotta believe these kids are, you know, they’re not. Do they go to scooter training? I don’t think so.
RON PHILLEO
I haven’t seen that yet.
MARK
Yeah,.
RON PHILLEO
Yeah. I mean. And yeah, you see them all over. So there’s. There’s people that own scooters, right? You have your own individual scooter, and then you have, like, the lime scooters that just are laying all over the street, and you can rent or throw in the river. Apparently people do that a lot, too. Seems like a popular pastime, but. Yeah, so there’s a lot of those scooters around. And the question is, what happens when people get hurt on them? You know, does liability go with. If it’s a rental company, does it go with them? You know, a funny thing is I’m on a race car team where we drive race cars and we have scooters on our hauler to get around the racetrack. A lot of times you’re covering a lot of ground. You want to go to a different part of the racetrack and the scooters are convenient. Well, one of our teammates brought one of a new scooter, and it hit speeds up to almost 40 miles an hour.
MARK
That’s not a scooter to me. It.
RON PHILLEO
Had dual motors on it.
MARK
Oh, my God.
RON PHILLEO
I got on this thing and I thought, if I die at the racetrack, it’s going to be on this thing, not in a race car. It’s. I mean, the power on these things is insane. There’s no training requirement, people don’t wear helmets. And sometimes people are under the influence on these things as well. So I don’t know. They’re really dangerous. Dangerous. And how they’re covered by insurance is so up in the air. I mean, insurance companies are trying to figure out how to deal with these things. It’s, it’s just kind of an unusual situation with those.
MARK
Well, does that, I mean, does that fall under a rider or umbrella policy or do you have to, you know, go get scooter insurance?
RON PHILLEO
God, I wish I had an answer for you because every carrier is a little bit different.
MARK
I didn’t find a lot on that either. Yeah,.
RON PHILLEO
No, and every, every scooter, I mean, the normal scooters go 17, 18 miles an hour. That’s. Those are the standard ones. And then you can get. I was actually looking online and you can get scooters that go over 60 miles an hour. I don’t think I’d want to be on 1 60, but they go over 60 miles an hour. They have double engines in them. I mean, they have shock absorbers, everything. And I honestly, you know, to get insurance for one of those, I, I’m sure we can find a company if we do it, but.
MARK
Yeah,.
RON PHILLEO
Imagine a lot of them want to do that.
MARK
I don’t think there’s a classification name for scooters either.
RON PHILLEO
There’s not. E Bikes have them. Ebikes have different classifications and most carriers under your homeowners policy will go up to class C, which is up to 28 miles an hour.
MARK
Okay.
RON PHILLEO
Scooters. Yeah, it’s. We don’t see a lot of guidance from carriers on those things.
MARK
Wow. So, yeah, let’s talk about something that people don’t really think about a lot and that’s the, the liability for your pet or your dog. And I know, I did some research on that. My daughter’s got two pit bulls and I told her a while ago that, you know, if your insurance company finds out you have two pit bulls, your insurance rates are going to go up. And she was like, why? Because her dogs are very friendly. You know, they’ve never bit anybody. I can’t see them doing that, but they’re intimidating. Yeah, they’re scary. She walks in with choke collars. When people see her coming, they go to the other side of the block.
RON PHILLEO
Yeah. She’s not going to have any problems with crime around her.
MARK
Yeah. But then, then she had an adjuster come to her house for a claim and he saw the Dogs.
RON PHILLEO
Yep.
MARK
And she said, dad, my insurance went up like 600 a year for the dogs.
RON PHILLEO
She’s lucky.
MARK
Yeah. Is that right?
RON PHILLEO
No, she’s lucky she doesn’t dropped immediately.
MARK
No kidding.
RON PHILLEO
There’s a lot of carriers that won’t even accept those dogs.
MARK
And then Rottweilers and Dobermans were up there too.
RON PHILLEO
Yeah. So there’s a restricted dogless by a lot of carriers. Rottweilers, Dobermans, pit bulls, Akitas. You know, there’s a lot of dogs that are on that list and even some smaller dogs that are just really aggressive chows are on there too. So a lot of carriers. They’ve just had so many problems with these mark of dog bites are so unpredictable. They can range from small emergency room visit to man, hundreds of thousands of dollars. So I know you and I were talking pre show and you know the dog last year, the dog bite claims over $1.8 billion.
MARK
Wow. I know my neighbor got bit by another neighbor’s dog and the neighbor’s dog had bit people before, had a history of it. And she got a settlement of $168,000. And you know, but here’s the sad part. She, she can’t even walk her dog anymore because she basically is disabled from the dog bite. You know, so the $168,000 to me was not a very good settlement, you know, to not be able to walk anymore or get outside of your house.
RON PHILLEO
Yeah. I don’t, I don’t think if your financial plan is to try to get an insurance settlement, you’re, it’s probably not a good idea because you’re going to be enduring a lot of pain and suffering somewhere along the way. If that, if that happens, if you get a big payoff from the insurance company, it’s because you. Something really bad go wrong, you know.
MARK
Yeah.
RON PHILLEO
And so it, it’s, the dog bite thing is really serious. I mean, we’ve had some interesting claims and sometimes the dog doesn’t have to bite anybody.
MARK
Really?
RON PHILLEO
Yeah. A dog can approach a bicyclist and he falls off his bike. A dog can jump up on your shoulders, knock you over. These are all considered dog claims and all liability claims underneath your homeowner’s policy. So it’s not even that the dog maybe bit you, maybe the dog was excited to see you and knocked you over and you know, you hit your head or you hurt your hip or whatever the case may be. So yeah, it’s. But the dog bite claims are interesting because we get people asking us about dogs all the time. And they say, well, you know, I have a pit bull, and there’s less dog bites by pit bulls than there are by Labradors.
MARK
Labradors don’t even come on the list of rated high up.
RON PHILLEO
Well, the funny thing is there are a lot of bites by Labradors. Well,.
MARK
There are a lot more Labradors.
RON PHILLEO
There’s a lot more Labradors. And that’s exactly. It’s the most common dog out there that’s considered a purebred type dog. So there’s more bites. Now, the thing that people confuse all the time with dogs is do you have a dog that bites or do you have a dog that’s prone to attack? And this is bred into the dog. Pit bulls. If you ever see a pit bull attack, they don’t bite. They grab on as hard as they can. They start to drag that person down, and they shake as hard as they can. Watch an attack by a pit bull. It’s totally different than a Labrador. A Labrador biting some. Most dogs bite to warn you, I’ve had enough of whatever you’re doing or I’m not feeling good about this. And they’ll snap at you.
MARK
Yeah,.
RON PHILLEO
Rottweilers, German shepherds, pit bulls, they don’t. Once they start,.
MARK
They grab on.
RON PHILLEO
And they don’t stop.
MARK
Yeah,.
RON PHILLEO
They’re attacking. They’re in attack mode rather than bite mode. And that’s the big difference. And that’s why those dogs on that restricted list are on there.
MARK
Yeah, interesting. So.
RON PHILLEO
And they cause severe damage at that point. It’s not an emergency room visit. This is, you know, we’re talking about reconstructive surgeries. Right. We’re talking about torn muscle tissues. We’re talking about a lot of things, you know, time off of work. These things get really severe. And disfigurements, you know, permanent disfigurement, which, by the way, juries hate permanent disfigurements, especially with children. If you disfigure a child with your dog, you’re going to be in for a big claim on that one.
MARK
Let me ask you this. How often do you see a dog, you know, dog claim or a trampoline claim or scooter that wasn’t disclosed on the application. And you’re dealing with that.
RON PHILLEO
See, our questionnaire is very extensive and we ask everybody about all of those things. Great thing, trampoline, right? Dogs, all these things. All these things that pose a hazard. So we ask that client up front. Now, once we have them insured and they get a dog, they buy a trampoline. Do they always call us?
MARK
No,.
RON PHILLEO
No, no. And it may not. Sometimes they don’t think about it. Sometimes they’re like, I’m not going to call. Either way, though, the insurance company is still on the hook now for this.
MARK
Okay.
RON PHILLEO
Now we, we did. At the time of underwriting, at the time of application, everything was disclosed. But people change things. People do things and they get trampolines, they get, you know, dogs that are prone to bite, all these things. And. And they didn’t call us.
MARK
Yeah. Okay. Well, do people understand the difference between flood and sewer backup and sump pump coverage? And what do you. How do you deal with that with your clients?
RON PHILLEO
No, nobody understands it until we explain it. Again. Here’s that education part again. Yes. People say, well, I did that flood insurance. I’m like, do you live on a river, really close to a lake level area, beach somewhere? No, no, I just. So, okay, I think what you’re referring to is sewer backup and sump pump failure. It’s one of the most common claims we see.
MARK
And that’s a right. That. What is that called? I mean, I know I have the sewer backup.
RON PHILLEO
Yep. That’s an endorsement on the.
MARK
Endorsement. Yeah.
RON PHILLEO
Because it is excluded from the basic policy and you can buy the coverage back through endorsement. And so it’s,.
MARK
It’s not expensive.
RON PHILLEO
It’s not that expensive. No. And it’s one we recommend to every client. Yeah. Some clients choose not to take it, whatever. But if you were involved in the last August. Right,.
MARK
Yeah, let’s talk about that. Or.
RON PHILLEO
Even this, even this April, we had big ones.
MARK
Oh, yeah, we did. Yeah. Yeah. So, yeah. The torrential downpours caused waterways and sewers to overflow, flooding homes and businesses throughout Milwaukee county and West Dallas. Home homeowners really, really got kind of caught off guard. I’ll say. Shocked. I don’t want to say they got screwed because, you know, again, it goes back to that education. Maybe they didn’t realize, but a lot of people, you know, lost a lot of money and there’s a lot of sump pump confusion, too. And flood versus water backup.
RON PHILLEO
Yeah.
MARK
So,.
RON PHILLEO
Yeah, there’s a lot of confusion. So I’ll give you the quick version. So some pump failure or sewer backup is water coming back up through a drain. Drains are supposed to work one way, right?
MARK
Yep.
RON PHILLEO
They’re supposed to take water away from your home, and when they don’t work the right way, they bring water into your home. So a sewer backup or a sump pump failure is an endorsement coverage. We can add that on now, people. People you brought up, are people confused by this? They say, I need that flood insurance. Well, flood insurance is typically defined as surface water coming into your home. So imagine water coming in through doors and windows. That’s. And it was on the surface. So the water was flowing from the surface into your home. And the sewer backup thing is water coming up through a drain. So two different things. Flood is only covered through the National Flood Insurance Program. They’re the ones that ensure that insurance companies administer it, but that’s. It’s underwritten by the flood insurance program. And most homes around here, unless you’re living on a river, don’t need flood insurance. I shouldn’t say don’t, because there’s always a chance. Or if you’re living at. At lake level, that’s when we see requirements for flood insurance. Most of the claims we saw after the heavy rains were sewer backup.
MARK
Okay.
RON PHILLEO
Or some pump failure.
MARK
Right. So I’m just wondering about lending someone your car. You know, what if you let somebody borrow your car, lend it to a relative, and what happens when they. Someone borrowing your car causes an accident? So your neighbor borrows your truck to move a couch and totals another car. Who. Who’s the insurance pay?
RON PHILLEO
Yeah, that’s a good question. So I would encourage everybody to do some serious underwriting when they give their keys away and say, is this person of high quality and character? Let them drive my vehicle.
MARK
You got to underwrite your neighbor’s family and friends.
RON PHILLEO
I wish everybody would, because we’ve had so many claims on this. Boyfriends using cars or, you know, distant relatives. Well,.
MARK
Yeah, and it’s. Why. Why do they need a car? You know, it’s like. I mean, that. First you got to get that question.
RON PHILLEO
Answered. Yeah. Why don’t you have a car and insurance and. Yeah, so. So, yeah, that’s. That comes up all the time. And we see claims on this all the time that someone’s driving that wasn’t. And it’s like, why was this person driving this car?
MARK
Yeah.
RON PHILLEO
And so the question is, is it covered if somebody borrows your car? If you give them permissive use, it’s called. That’s how it’s referred to in the insurance industries. If you. If you give them permission to use your vehicle. Yeah. Let’s say, you know, Ro. You say, hey, can I borrow your car today? And I say, yeah, here it is. You’re covered. All right. Even though you’re not listed on my policy because I gave you permission to use the vehicle. Now the question comes. Let’s say you’re my roommate and my keys are always laying on the counter. And I say, yeah, if you ever need a car, bosh, borrow mine. Now you actually become one of the drivers in the household at this point because you have access to this car constantly rather than a lot, rather than a one off scenario. So now the insurance companies, if you have access, if you’re driving the household or someone has access to this vehicle all the time, the insurance companies want you listed on that policy. They’re going to run your motor vehicle record, they’re going to run your claim history and they’re going to rate for you at this point. Whereas if I borrow your car or you borrow your pickup truck to move something, that’s a one off thing. I don’t have access to your car on a regular basis. It’s not a big deal. But if you use someone’s car on a regular basis or you have access to it on a regular basis, the insurance company wants to know about that.
MARK
Interesting. So. So five ways to save on insurance without sacrificing protection, deductibles, bundling payment options, insurance scoring and eliminating unnecessary coverages. So talk about that a little bit. I mean, people always are looking to save money, but you know, you don’t want them to lose coverages that are going to be critical down the road that they’re not anticipating to. How do you balance that?
RON PHILLEO
Yeah, that’s a conversation we have with our clients constantly. Several times a day people are calling us, I need to save some money on my insurance or how do I say, you know, my rates are high and insurance is expensive and we understand that. We take our clients premiums incredibly serious as we do their coverage too.
MARK
Right.
RON PHILLEO
And so you’re right, it’s a balancing thing. One of the things that I’m always concerned about is liability. Liability is the wild card. And I’ll give you an example. Let’s say you have a car that’s, I don’t know, 15 years old. All right. And that car is worth, let’s call it $5,000.
MARK
Yeah.
RON PHILLEO
All right. You can choose to carry collision on it. So if it’s destroyed in an accident, you can choose to carry comprehensive if it’s stolen and whatever, and we’ll pay you out on that minus your deductible. Right. But your loss is set. We know that if you didn’t have collision on that car or you didn’t have comprehensive it was stolen, that it’s a $5,000 loss.
MARK
Yeah,.
RON PHILLEO
It’s, it’s a Predetermined size loss. Right. And we can deal with that. Liability is the thing that I’m always concerned about with my clients. If you hurt somebody in an accident, Mark, what’s that going to cost?
MARK
I have no idea.
RON PHILLEO
It’s a wild card. It depends who you hit, what you do. I mean, there’s a million things that can happen. Right. And so I never want my clients to cut back on liability coverage. Do not get rid of your umbrella. Do not cut. Lower your liability rates on your auto, in your home. These are the things that are going to. I call them bankruptcy coverages.
MARK
Yeah, I get it. I get it. I’ve always had it.
RON PHILLEO
Yeah.
MARK
Yeah. And, you know, I mean, I insured a lot of. A lot of people. A lot of young people and a lot of people of. Well, I can’t say it, but a lot of people.
RON PHILLEO
Yeah, well, I know, I know you’ve had your shares of, you know. Yeah. Well, you know, you had some young kids, and that tends to drive that activity a lot. But.
MARK
Oh, the kids are so hard to. They’re so hard to insure.
RON PHILLEO
Yes. And not only that, they present a huge liability exposure. So please, when we’re talking about saving money, if you want to drop collision on a car and say, I can afford to take this loss, that’s fine. I focus on the bankruptcy coverage. Just things like uninsured and underinsured motorists, liability coverage, just having the umbrella. These are the things that are going to bankrupt your family. A $5,000 loss on an old vehicle probably isn’t going to make a. It’s not. It’s not a fun day,.
MARK
But.
RON PHILLEO
It’s not going to put you in bankruptcy.
MARK
Well, and the other thing is, I mean, one of the things. We’re getting close to running out of time, but we’re not out of time yet. But one of the things that I did was when the claims were smaller and I. And anything less than $2,000, I was paying out of pocket.
RON PHILLEO
We encourage that. As much. Keep as much activity off your record as possible.
MARK
I remember one of my daughters had an accident. She was actually elder. You know, she was an adult. And. And she got the. The other woman that hit her in the Target parking lot, she got her dad’s number and she said, call my dad. He’ll take care of it. And my daughter said, dad, would you call him, please? And I was like, no. I go, you got to start learning how to do these things. I can’t do it for. You know, you’re 20 years old now. And it was like. So I called the guy and I say, look, you’re my daughter, and your daughter apparently had an accident up in Minneapolis in the Target parking lot. And apparently your daughter hit my daughter. He goes, yeah, yeah, yeah, yeah, I know. Just. Just go get a couple estimates and call me back. And I said, well, I already did. I got a couple estimates. And he goes, give me the. Give me the higher one. And I said, well, that was 868. He goes, okay, how do you spell your name? And he starts writing the check, you know, and I’m like, oh, my God, you know, how many children do you have? And you. She’s my fourth. I said, oh, my God. So you’ve done this before? He’s like, yeah, yeah, I’ve done it before. Hey, Ron, thanks for being on the show. And you’re going to be back for the third segment on insurance. We’re going to cover ELPI and Workman’s Comp.
RON PHILLEO
Yeah, a little commercial stuff. Absolutely. I love being on the show.
MARK
Yeah. No, it’s fun having you. You’re so knowledgeable and it’s an easy conversation with you. So you’ve been listening to the Robo Show. I’m your host, Mark Robot. I’m with guest Ron Philleo of the Philleo Insurance Agency, independent broker in Brookfield, Wisconsin. Thanks for listening to the Robo Show on WXRW 104.1 FM. Riverwestradio.com. Have a great evening. Hope you listen in next week. Okay. Another great show. Thanks.